In some ways I’m as productivity-obsessed as ever. What’s changed, and it’s a big change, is that I no longer take myself to be en route to some final state in which I’ll have discovered the best system, and can feel good about myself at last.
I’m convinced it’s a balm for much of what stresses us out: “the compulsion to closure,” which is the hope that all of this is leading up to some kind of permanent resolution. It isn’t. It’s better than that: you get to just be here, and do stuff.
The lack of resolution feels like a problem that needs solving. But have you considered the possibility that the only problem is your belief that such tensions might ever get resolved?
Living without hope of resolution is liberating because it removes a terrible weight from your actions and decisions – the weight that arises from the feeling that they must always be moving you toward some settled state. (Which often just leads to procrastination, since you’re unsure which action would be most helpful for getting you there.)
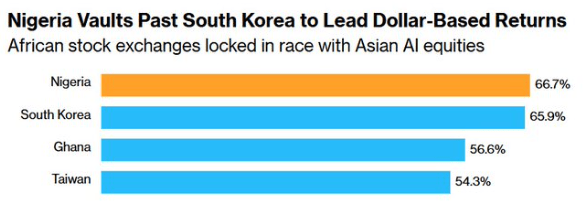
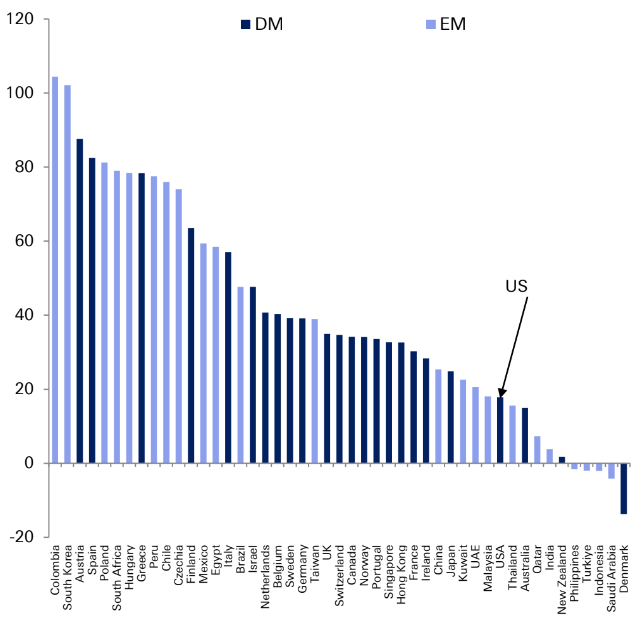
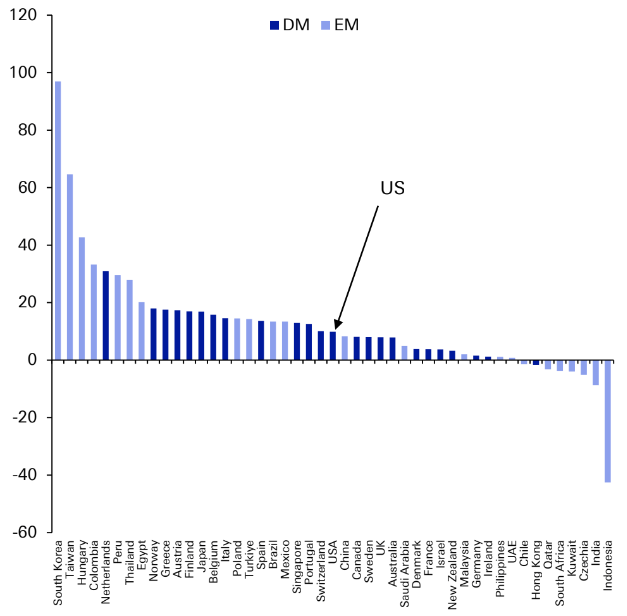
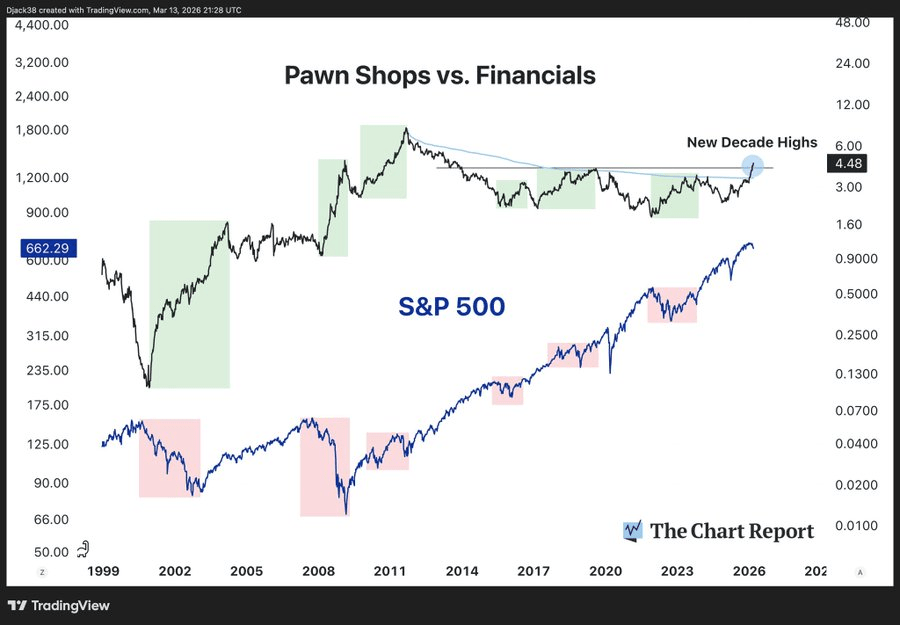
Nigeria now has the best performing stock market in the world, taking the lead over South Korea. As of the end of 2025, there were over 5,000 ETFs, mutual funds, and CEFs that focused on U.S. stocks. There used to be one ETF that invested in Nigerian stocks, but it closed back in 2023 because no one owned it.
__________________________________
2025 Returns:
2026 Returns:
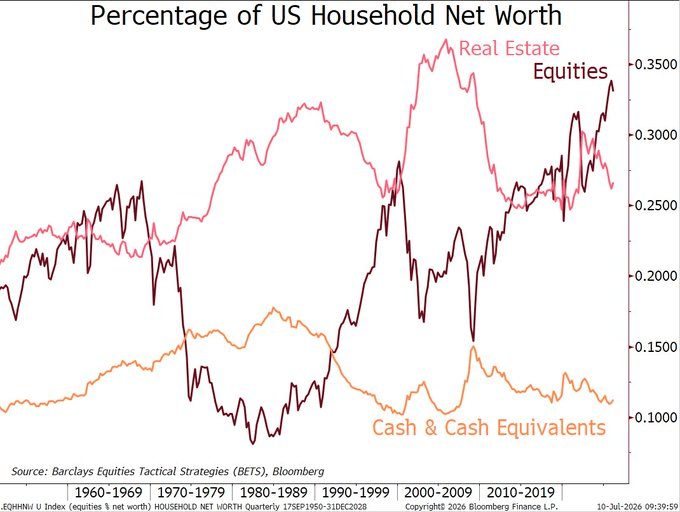
As U.S. stock prices continue to rise into the stratosphere, the percentage of U.S. household net work in stocks (equities) is higher than any point over the last 80 years.
The difference between forward earnings earnings (where analysts project S&P 500 stocks’ earnings will be a year from now) and trailing earnings (what S&P 500 stocks’ earnings actually were over the last year), has rocketed up to record bullish extremes.
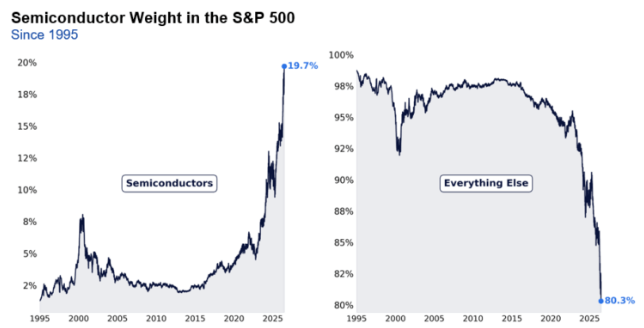
The defining story of the first half of 2026 was not a macro shock, it was the continued structural transformation of equity markets
Market concentration remains near historic highs. Passive investing continues to absorb capital at unprecedented rates. Retail investors have become a persistent source of demand. Leverage has migrated toward increasingly short-dated and concentrated exposures. Together, these forces are reshaping liquidity, price discovery, and the behavior of volatility.
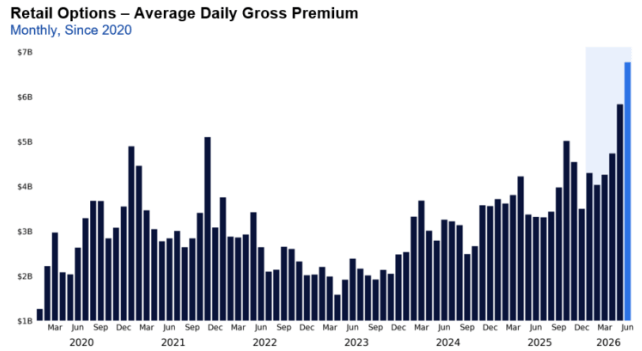
Retail investors have poured into stock options in 2026:
Unlike previous periods of elevated retail activity, today’s retail investor is increasingly concentrated in the same sectors driving benchmark performance, led by semiconductors and broad-based ETFs.
In June alone, retail traded approximately $1.9 billion of semiconductor options premium per day (6x the historical average) with about 75% of that activity concentrated in call options.
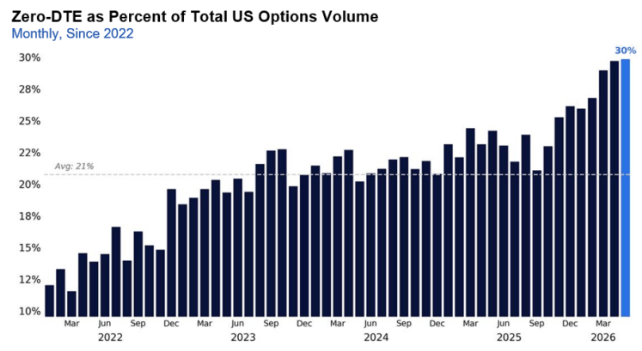
One out of every three listed options traded in the US now expires the same day, roughly doubling zero day options’ market share since daily expirations launched in 2022.
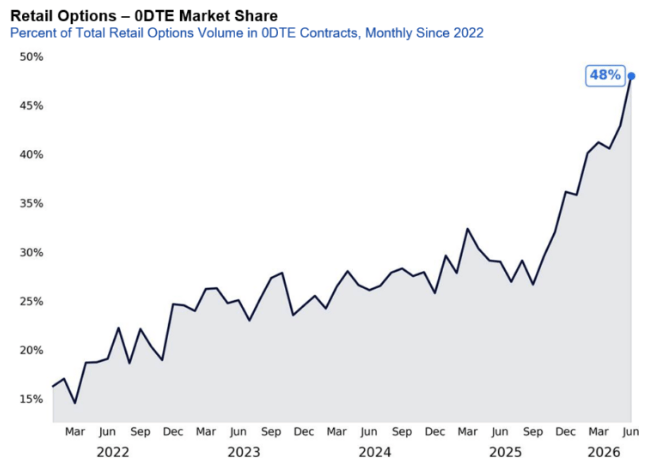
Following the introduction of Monday and Wednesday expirations in single stocks at the beginning of this year, nearly half of all retail options volume executed by Citadel Securities now trades in zero day contracts, up from 30% in 2025 and just 13% in 2021. Average time to expiry on Citade’s platform is less than 3 days.
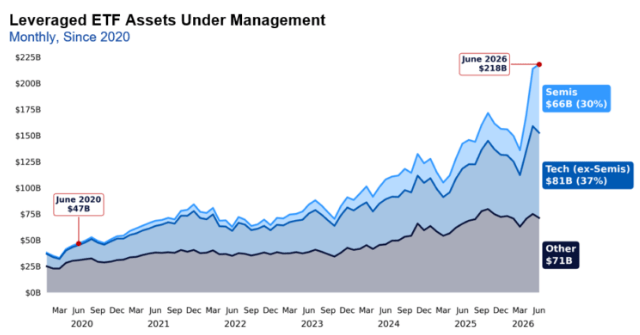
Investors chase what’s hot (semis and tech) with leveraged ETFs:
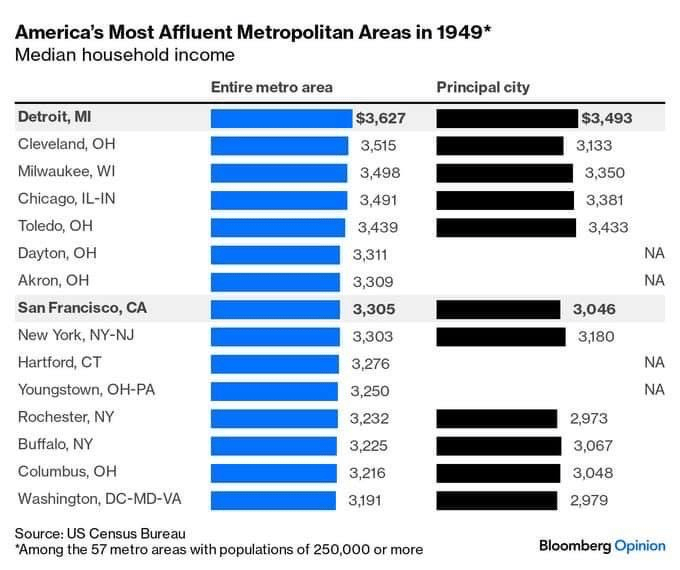
In 1949, four of America’s seven richest metro areas were in Ohio. Cleveland, Toledo, Dayton and Akron were out-earning New York, San Francisco and DC.
Money is less of a factor in attraction than people think. What matters more is your ambition. The academic literature on evolutionary biology supports this. In a study across 37 cultures, evolutionary psychologist David Buss found that, on average, potential partners valued “ambition and industriousness” more than “good financial prospects” when choosing a mate.
In evolutionary terms, this is known as Resource Holding Potential (RHP), or your ability to acquire resources in the future. A husband signals high RHP while working, but signals low RHP if he retires early, gets high and plays video games with friends all day; even if he worked unbelievably hard to get to that point. Why is ambition more attractive than money?
Because money says, “I was useful,” while ambition says, “I am useful.”
People care about the future. People care about the genes they pass on to their offspring. And they want to pass on traits like industriousness because those traits will help their children acquire future resources, and so on. Having money makes you more attractive. But it’s not the money that’s actually appealing, only how you acquired it. The potential to collect more resources is the draw from potential mates.
A loser’s game is any game, contest, or activity in which the ultimate victor is determined by the actions of the loser. These contests are not won; they are lost.
In tennis, pros can be aggressive. They have the skill, precision, and experience to place shots just outside their opponent’s reach. They play a winner’s game. The match goes to the player who earns the most wins. Amateurs, however, often lose by trying to play like the pros, because it leads to unforced errors. It’s a loser’s game. Amateurs win in tennis by volleying until their opponent hits it into the net or out of bounds. They win by not losing.
There are two different games being played in the stock market. The game the experts play differs from the game the amateurs play. The game amateurs should play, and many experts too, is built on a foundation of avoiding errors. Essentially, not losing. Fewer errors lead to better results.
Luck
Every investor should recognize the powerful potential impact of luck — not good luck, but bad luck. We can all live through good luck. But bad luck — the apparently random occurrence of adversity — is equally prevalent, and its consequences can be far greater.
Getting Excitement Out of the Market
Go to a continuous-process factory sometime — a chemical plant, a cookie manufacturer, a place that makes toothpaste. Everything is perfectly repetitive, automated, exactly in place. If you find anything interesting, you’ve found something wrong.
Investing is a continuous process too; it isn’t supposed to be interesting. It’s a responsibility. If you go to the stock market because you want excitement, then sooner or later you will lose. Everyone who thinks the stock market is a game loses — everyone, to the last man, woman, and child. So, the purpose of an investment policy is simply to ensure that your continuous process never breaks down.
On Over-Confidence
A rapidly rising market makes you forget that those whom the gods would destroy, they first make confident. The more you know, the higher the odds that you’ll make a serious mistake. That’s why it’s not the beginners who tend to die at skydiving and why most car accidents happen within a few miles of home. There’s a saying in the British Royal Air Force that investors need to remember: “There are old pilots, and there are bold pilots, but there are no old, bold pilots.”
As human beings, particularly if we are successful in other parts of our lives, we are notoriously unable to accept the obvious reality that, on average, we are average, and that our normal experiences will usually be about average because we are, as a group, captives of the normal distribution of the bell curve. Studies all the time show we think we are above-average drivers, above-average parents — and above-average investors. And we do tend to take it personally when our stocks go way up or go way down, even though, as Adam Smith admonishes, “The stock doesn’t know you own it.”
________________________
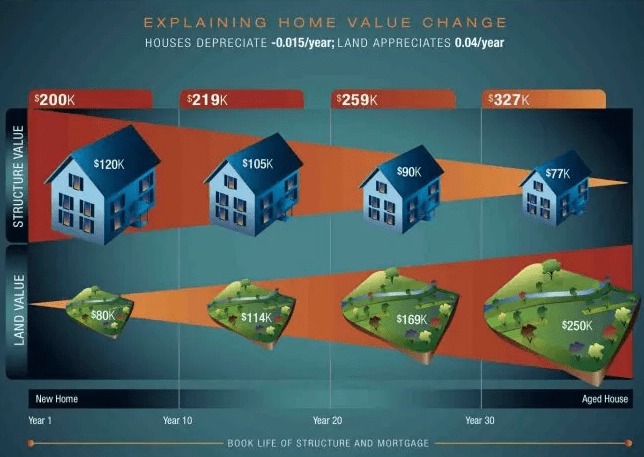
Land Appreciates. Homes Depreciate.
The value of a home (excluding land) declines over time unless it is updated to break even. Think of it in the context of not updating the home for 30 years, which makes the concept much easier to understand. The house will slowly fall apart. Meanwhile, in most housing markets, land values eventually rise over a 30-year period, and the cash-poor homeowner can sell for more than their original purchase price.
__________________________
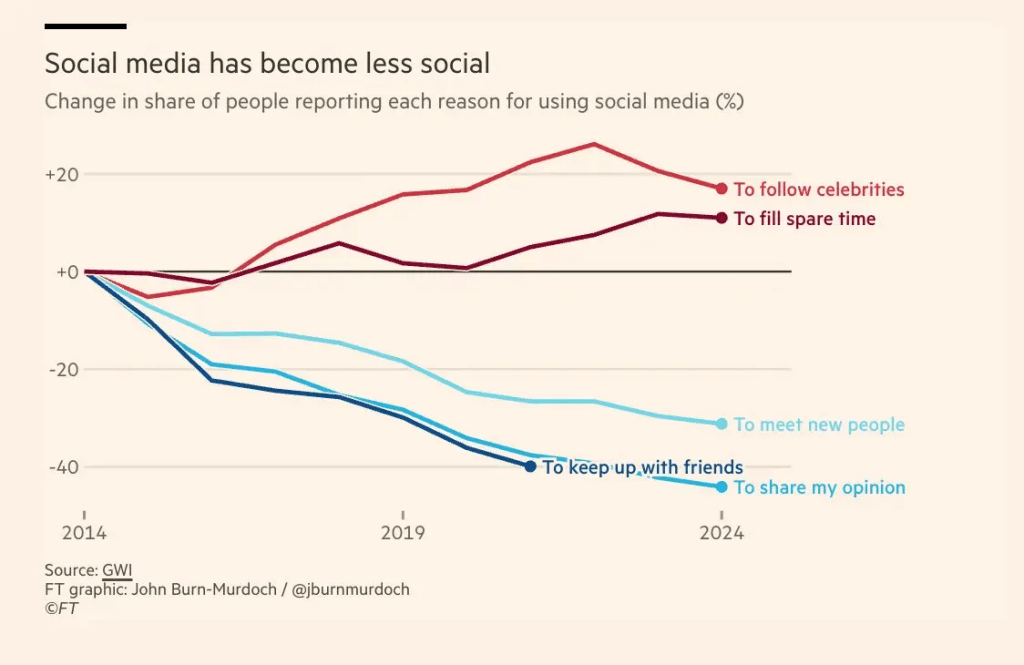
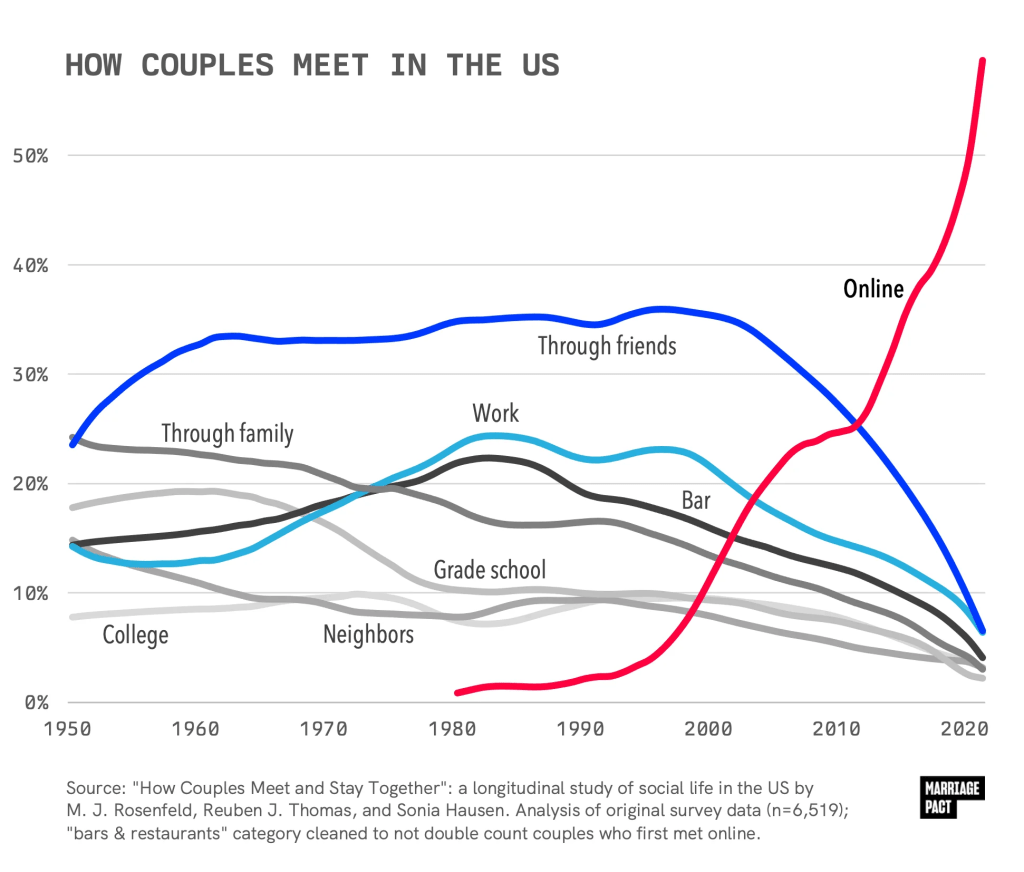
Social media has become less social.
__________________________
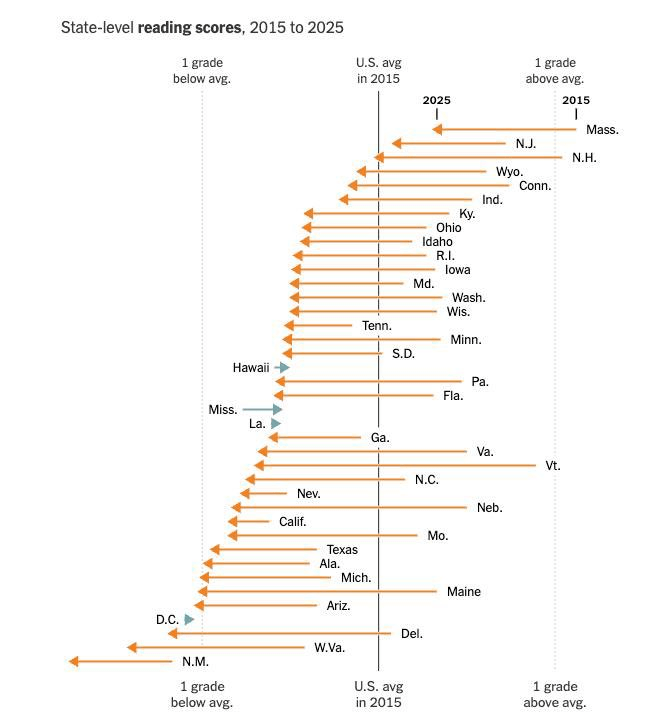
State level reading scores have dropped dramatically over the last 10 years.
__________________________
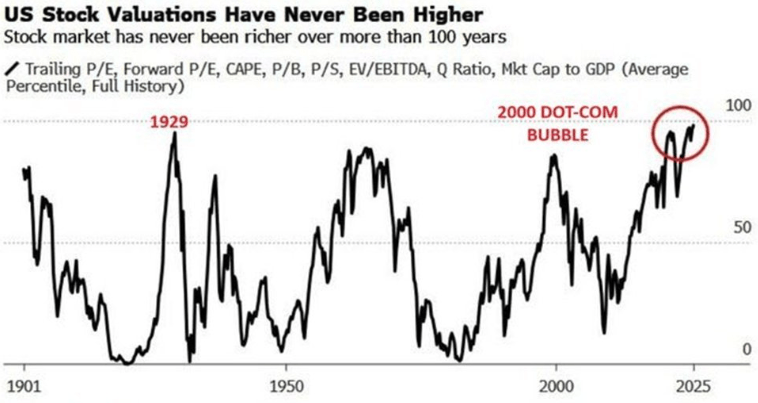
Based on an average the average of the valuation metrics below, the U.S. stock market has now become more expensive than both the 1929 and 2000 bubble peaks:
Trailing (P/E) Price to Earnings
Forward (P/E) Price To Earnings
Cyclically Adjusted Price To Earnings (CAPE)
Price to Book (P/B)
Price to Sales (P/S)
Enterprise Value (EV) to Earnings Before Interest Depreciation & Amortization (EBITA)
Market Value to Replacement Cost Of Physical Assets (Q Ratio)
Market Cap to GDP
_________________________________
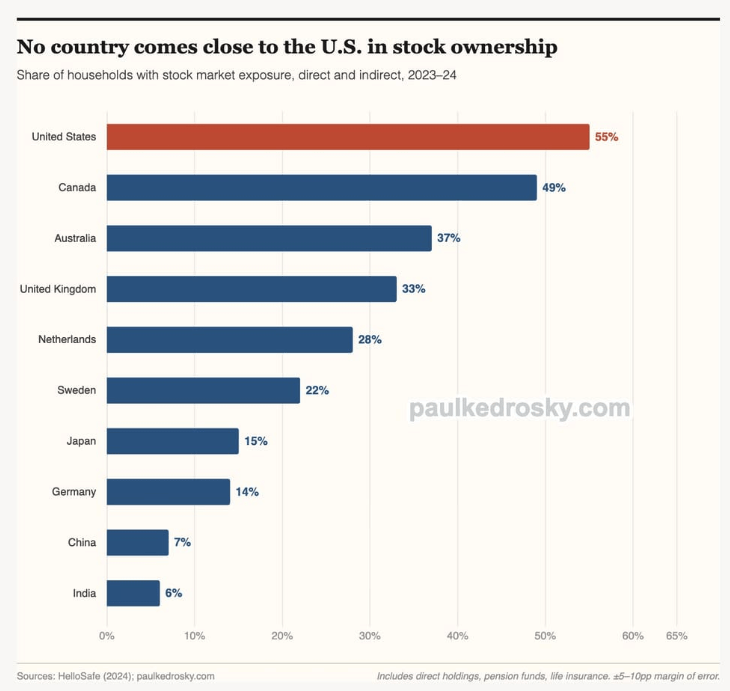
U.S. households are far more invested in stocks relative to the rest of the world:
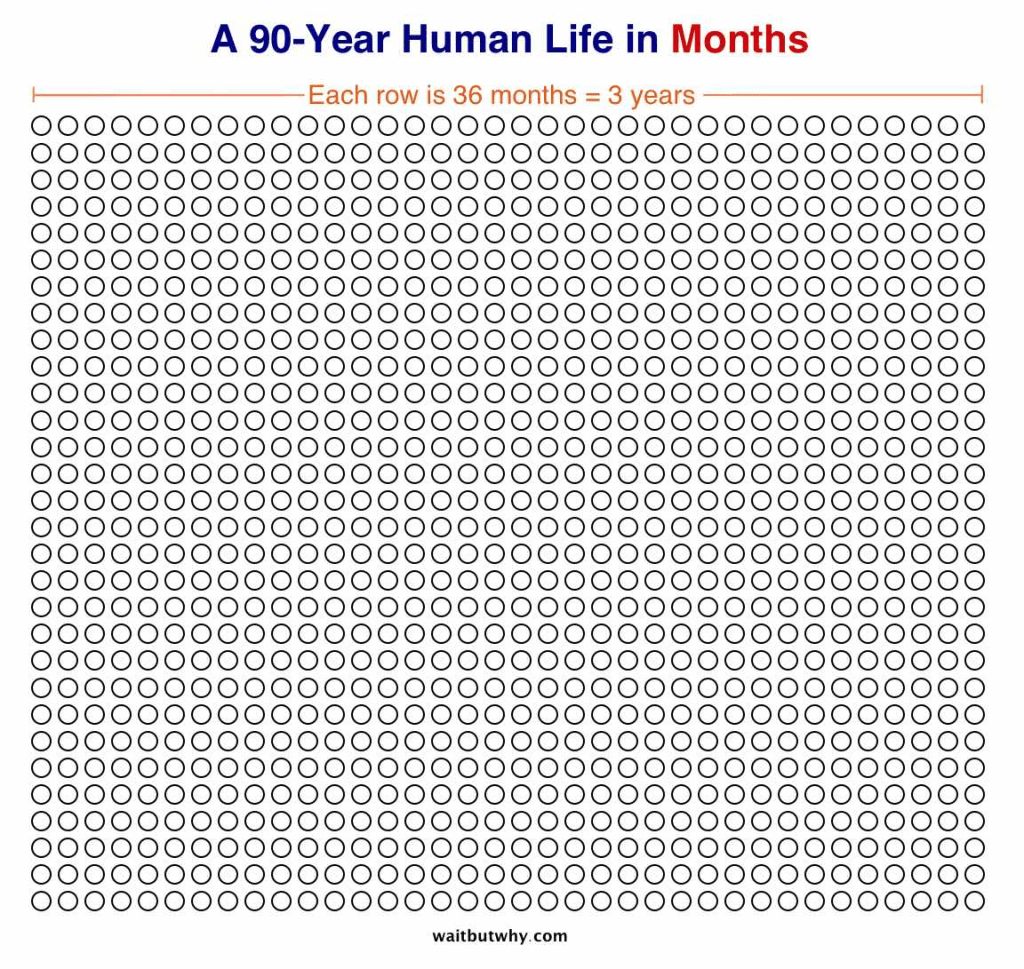
When the average person graduates from high school, they’ve already used up 93% of the total in-person time they’ll ever spend with their parents. They’re already in the tail end.
The same often goes for old friends. In high school or college, you hang around the same group of friends about five days a week. In four years, you probably rack up 700 group hangouts. Now, scattered around the country with totally different lives and schedules, you’re probably in the same room at the same time only 10 days each decade. The typical person leaving college is already in the last 7% of the time they’ll ever spend with their friends.
What do you do with this information? There are three main takeaways:
1) Living in the same place as the people you love matters.You probably have 10 times the time left with the people who live in your city as you do with the people who live somewhere else.
2) Priorities matter. Your remaining face time with any person depends largely on where that person falls on your list of life priorities. Make sure this list is set by you—not by unconscious inertia.
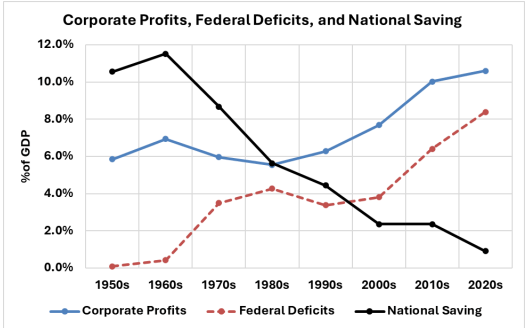
U.S. corporate profits and stock market valuations are at historic highs, but the kind of real, productive investment that’s supposed to create those profits (building factories, equipment, infrastructure, etc.) has been falling for decades. Why have U.S. corporate profits and equity valuations reached historic highs despite a concurrent secular decline in net domestic investment?
In the mid-20th century, profits came from companies investing money to build things, sell more, and earn returns. Today, profits keep climbing even though companies aren’t really investing more in the real economy. So where are the profits coming from?
Federal budget deficits are the source. The government is essentially borrowing money and pumping it into the economy through programs like Social Security and Medicare, and that money flows almost dollar-for-dollar into corporate profits — which then get recycled into the stock market, inflating share prices.
Net Corporate Profits = Net Domestic Investment + Government Deficit − Household Saving − Foreign Saving.
This is just bookkeeping — it has to be true by definition. A government deficit is negative saving. When the government spends more than it takes in through taxes, it stimulates income and profits.
Here’s how it works in plain terms:
The Treasury issues bonds and uses the money to send entitlement checks (Social Security, Medicare, etc.) to households
Those households (mostly middle and lower-income, who spend nearly everything they get) go out and buy goods and services
That spending shows up as revenue at corporations
Because the spending didn’t require companies to spend more on production, most of it drops straight to the bottom line as profit
The wealthy people who originally bought the Treasury bonds basically just swapped cash for a Treasury bond — they didn’t lose anything. But the Treasury’s spending stimulates real consumption, which becomes corporate profit.
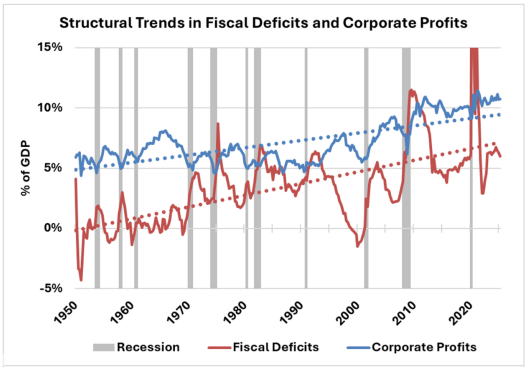
There’s a nearly one-for-one long-run relationship between fiscal deficits and corporate profits. In other words, every additional dollar of deficit roughly translates into a dollar of corporate profit over time. However, if you just look at quarterly correlations between deficits and profits, you’ll see a negative relationship — that’s because during recessions, profits collapse and deficits spike at the same time. But that’s a short-term cyclical effect that masks the long-term structural relationship.
The “natural experiment” occurred when the U.S. government briefly ran brief budget surpluses in the late 1990’s, withdrawing net spending from the economy. During this period of declining deficits and brief surpluses, corporate profits fell too. But with the recession in 2001, fiscal deficits returned and profits immediately resumed their upward climb.
What Happens Then?
Once corporations have these excess profits, what do they do with them? Here’s where the second half of the financialization story kicks in.
In a healthy economy, companies would reinvest profits into expanding production. But for decades, the returns on real investment haven’t been attractive enough to justify it (due to global competition, especially from China, weak domestic demand, etc.). So instead, firms returned profits to shareholders through dividends and buybacks.
Those distributions go mostly to wealthy households — and wealthy households don’t spend most of that money on goods and services. They reinvest it in financial markets, often through passive index funds. Mandated to remain fully invested, these funds then recycle the inflows to purchase stocks in proportion to their market capitalization indifferent to valuation, thus bidding up prices without any change in fundamentals.
In other words, an index fund doesn’t ask “is this stock cheap or expensive?” — it just buys mechanically. So when more money flows in, prices get pushed up regardless of underlying fundamentals. Research shows that each $1 of inflow increases market value by roughly $5 — meaning passive flows have an outsized impact on valuations.
How Did We Get Here?
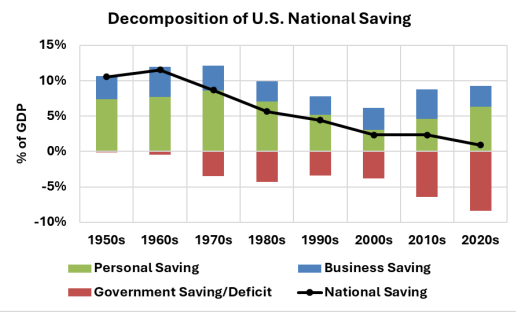
1. The collapse of national saving. In the 1950s and 1960s, net domestic investment, funded entirely by national saving, averaged 11% of GDP. But then structural fiscal deficits started to offset private saving, and national saving has now collapsed to nearly zero.
2. The long decline in interest rates. Two big forces pushed rates down: China joining the WTO in 2001 (which created huge trade surpluses that flowed back into U.S. Treasuries) and the post-2008 era of zero interest rate policy and quantitative easing. Cheap borrowing costs let the government run big deficits without “crowding out” private investment.
3. The shift from tangible to intangible investment. Gross domestic investment ebbs and flows with the business cycle, but its longer-term average has held relatively steady, only slipping from about 23% of GDP during the 1950s to 1980s to about 21% in recent decades. Net domestic investment has declined from nearly 11% of GDP in the mid-twentieth century to about 5% in recent years. Over the same period, depreciation rose from roughly 12% of GDP to more than 16%.
The reason: today’s “capital” is software, data, servers, and R&D — which depreciates and goes obsolete much faster than the factories, machines, and infrastructure of 50 years ago. So companies have to spend more just to replace worn-out capital, leaving less for genuine expansion.
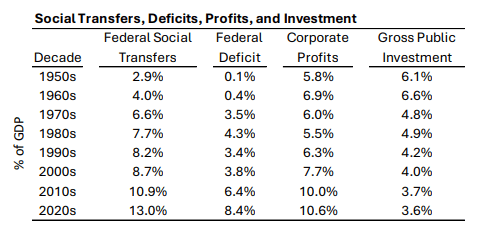
4. The financialization of profits. As deficits soared from near zero in the 1960s to 8% of GDP by the 2020s, the profit share grew in parallel, from 6% of GDP to more than 10%. Over this same time, national saving collapsed from 11% of GDP to near zero.
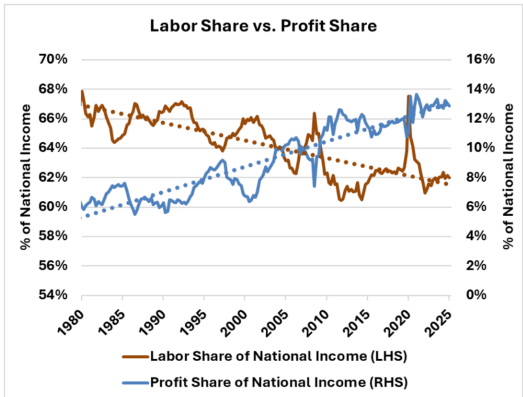
5. Growing inequality as a consequence. Because the profit share of GDP grew, the labor share necessarily shrank. Even as social transfers soared by 10% as a percentage of GDP, the labor share of national income entered a prolonged decline, falling from near 68% in the early 1980s to 62% by the mid 2020s. And because the rising profits accrue mostly to wealthy households, who don’t spend much in the real economy, this further fuels the cycle of recycling profits into financial assets.
There are competing theories for why corporate profits have grown so much — the “superstar firm” hypothesis (industry consolidation gives dominant firms pricing power), globalization (cheap foreign labor crushed wages), and the rise of high-margin tech companies with intangible-heavy business models.
While part of the equation, these factors operate within the larger macroeconomic environment established by fiscal and monetary policy. In other words: those theories explain which companies win, but the deficit story explains why the total pie of corporate profits has grown so much faster than the underlying economy.
What This Means Moving Forward:
The foundation supporting U.S. corporate profits and equity valuations has weakened, leaving the market increasingly fragile. Profits now depend on large-scale fiscal deficits, a sharp departure from the mid-century model when profits were generated by private investment of retained earnings.
Today’s stock valuations rest on continued (and growing) fiscal deficits. If at some point the U.S. is forced — by the bond market, by political will, or by a debt crisis — to reduce deficit spending, the entire mechanism that’s been propping up profits and stock prices could go into reverse.
Reversion to a healthier macroeconomic environment of declining deficit spending and greater net investment may cause sharp declines in both corporate profits and valuation multiples and likely trigger a financial crisis with politically toxic consequences. Ironically, the more palatable option may be to remain on the current path until a financial crisis imposes on us the discipline that we are unwilling to impose on ourselves.
Life insurance companies manage huge pools of money. When you buy a life insurance policy or annuity, they take your premiums and invest them so they can pay you (or your family) decades later. These are long-term promises, so it really matters that the money is managed safely.
Unlike banks, which are regulated by powerful federal agencies, insurance companies are regulated state by state. Each state has its own rules and a much smaller budget. Some states (like Vermont) offer very lenient rules to attract business. The result is that insurers can shop around for the weakest oversight — and state regulators are simply outgunned compared to the companies they’re supposed to watch.
Insurance companies used to be boring and conservative. But in recent years, big private equity (PE) firms have bought up many of them. The PE firm is like a slaughterhouse that now owns the sausage factory. Instead of stuffing the sausage with quality meat (safe, plain bonds), they’re tempted to dump in their own leftover scraps (risky, hard-to-sell private credit deals) — because they control both sides of the transaction.
The PE firm originates risky loans, then has its own insurance company buy those loans. The PE firm collects fees and gets a guaranteed buyer for its products. But if those investments go bad, it’s not the PE firm that loses — it’s the insurance policyholders whose money was backing those investments.
The Hidden Risks:
Maturity Mismatch: Insurers are using shorter-term money to fund long-term, hard-to-sell investments. That works until people want their money back all at once.
Captive Reinsurance: Insurers are shuffling liabilities to affiliated shell companies (sometimes offshore) that don’t actually have enough real capital behind them. This makes the insurer look healthier on paper than it really is.
The economy and credit markets have been strong. When times are good, risky bets don’t look risky. But cracks are forming — defaults are rising, and some funds have already started blocking investors from withdrawing money.
Researchers created modified versions of psilocin — the active form of psilocybin from “magic mushrooms” — that still target key serotonin pathways linked to depression and other brain disorders but appear to cause far fewer psychedelic-like effects.
Private equity (PE) firms have been buying up about 10% of US life insurance companies since 2020. They’re then using the insurance companies’ money (called the “float” – money from premiums that hasn’t been paid out yet) to make risky loans to struggling businesses.
They’re using a private ratings agency to label these risky loans as safer than they actually are. This fake safety rating lets them:
Hold less cash in reserve (normally you need more reserves for risky investments)
Legally invest in things they otherwise couldn’t
Many of these loans are going bad – about 10% are already defaulting. The companies that borrowed the money are often unprofitable startups (especially software companies) that can’t actually pay back their debts. Some are even “zombie companies” kept alive artificially.
How the Fed raising rates in 2023 amplified this problem:
Fed Raises Rates → Government Borrowing Costs Go Up
When the Fed raised interest rates, it became more expensive for the US government to borrow money
The government pays interest on its debt, so higher rates mean higher interest payments
This caused the government’s budget deficit to balloon by 3% of GDP in 2023
Bigger Deficit → More Treasury Bonds Issued
To cover this bigger deficit, the government had to issue more Treasury bonds
These bonds became “fresh collateral” – basically, new assets that could be used as backing for loans
The RRP Money Gets Unlocked
There was $2.5 trillion sitting in something called the Fed’s “Reverse Repo Program” (RRP) – think of it as a parking lot for cash
Normally this money just sits there safely
But with all these new Treasury bonds available, financial institutions could use them to borrow against in “repo markets” (short-term lending markets)
PE Firms Borrow This Money
The private equity firms and their various entities (the “layers of the leverage cake”) were able to tap into this massive pool of money
They used it to fund more and more risky loans through the insurance companies
Instead of letting the economy cool down (which is what rate hikes are supposed to do), the Fed accidentally created a situation where trillions of dollars flowed into this problematic private equity scheme.
Who Gets Hurt: Foreign banks and insurance companies:
Foreign Institutions Bought the Debt
These PE firms and BDCs (Business Development Companies – investment funds that make these risky loans) didn’t just use insurance company money
They also borrowed money from banks and sold bonds/securities to investors
Foreign banks and insurance companies in countries like Japan and Germany were major buyers of these securities
Why Foreign Buyers?
Japanese and German institutions are from “surplus creditor nations” – countries that save a lot and invest globally
They’re always looking for places to invest their money
US securities seemed attractive, especially ones with good (fake) credit ratings
They’re Holding the Bad Loans
When these loans start defaulting (which the author says is already happening at 10%+), the value of those securities plummets
The foreign banks and insurers who bought them will take massive losses
They Don’t Know Yet
Stocks of these foreign financial institutions are “at all time highs”
Meanwhile, US-listed PE firms and BDCs have already collapsed in value
This suggests the foreign institutions haven’t realized their investments are worthless yet – the losses are hidden in complex financial structures
Foreign banks and insurers thought they were buying safe, well-rated US investments. Instead, they’re holding bags of loans to failing startups and zombie companies. When they finally discover this (mark their books to reality), their stock prices will crash too. It’s like they bought what they thought were AAA-rated bonds, but they’re actually subprime loans in disguise.
In Summary: This is as a massive, ticking time bomb of bad debt hidden inside insurance companies, enabled by sketchy ratings and Fed policy.
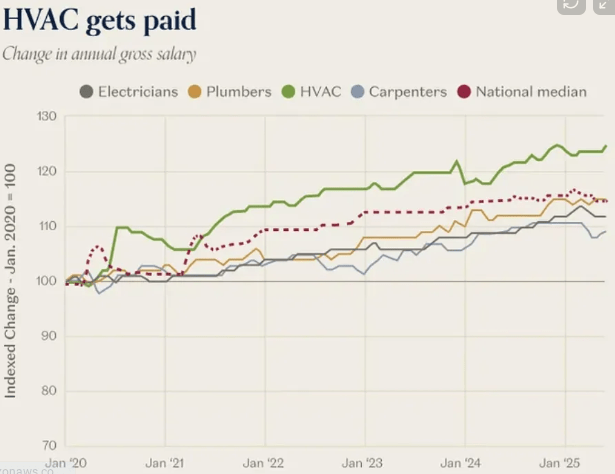
Weird things happen to economies when you have huge bursts of productivity that are concentrated in one industry. Obviously, it’s great for that industry, because when the cost of something falls while its quality rises, we usually find a way to consume way more of that thing – creating a huge number of new jobs and new opportunities in this newly productive area.
But there’s an interesting spillover effect. The more jobs and opportunities created by the productivity boom, the more wages increase in other industries, who at the end of the day all have to compete in the same labor market.
Our explosion of demand for data centers means there’s infinite work for HVAC technicians. So they get paid more (even though they themselves didn’t change), which means they charge more on all jobs (even the ones that have nothing to do with AI). Furthermore, the next generation of plumber apprentices might decide to do HVAC instead; so now plumbing is more expensive too. And so on.
Academics have published new research on the impact that Short Form Videos (SFV) like TikTok, Instagram Reels and Youtube shorts have on cognitive and mental health. The report systematically reviews and analyzes 71 studies involving over 98,000 participants.
SFV use is linked to poorer cognitive performance, with the strongest deficits in attention and inhibitory control, suggesting users struggle to focus and suppress impulses.
Frequent exposure to fast-paced, highly rewarding SFV content may rewire attention systems, fostering “rapid disengagement” from tasks that are slower or require sustained effort, reducing cognitive endurance over time.
SFV use is associated with poorer overall mental health, with the strongest links to stress and anxiety, indicating consistent emotional strain among heavier users.
Heavy SFV use reinforces impulsive engagement loops driven by dopamine rewards, contributing to compulsive scrolling and difficulty disengaging, patterns resembling behavioral addiction.
Short-form video consumption is associated with poorer sleep quality, especially when used at night, due to overstimulation and blue light disrupting melatonin, which can worsen mood and cognitive functioning.
Higher SFV use correlates with increased loneliness and reduced life satisfaction, as digital interactions replace real-world social connection for some users.
Negative effects occur across both youth and adults, meaning the cognitive and emotional risks of SFV use are not limited to developing brains; adults experience similar declines and mental health associations.
_______________________________
These days, it’s all stocks all the time, with reputable authorities calling on small investors to put everything they have saved into equities. Older investors are reminded of the mantra so common in 1999: “Every penny you don’t have invested in stocks will hurt you.”
More than a generation ago, financial historian Peter Bernstein wrote about investors’ “memory banks,” the market experience that accumulates in their hippocampi over their investing lives and molds their investment strategy. As he put it, looking back on the 1990s: “Most of the new participants in the market had no memory of what a bear market was like.”
And here we are today, almost seventeen years into a great bull market. Rather like 1999, also seventeen years into a long-term bull market, or 1966, once more seventeen years. Or 1873, sixteen years in, or 1837, eighteen years in, or 1893, twenty years in — to name a few of the notable tops over the past two centuries. Just long enough to produce empty memory banks in just enough investors.
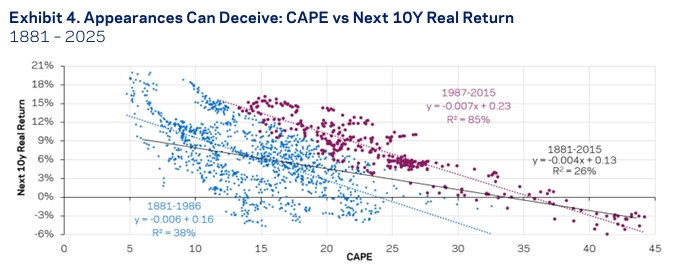
Historically, valuations have been a useful (though not perfect) indicator of real returns over the following decade. Below, you’ll see historical CAPE readings (in black) for the U.S. market alongside their corresponding forward ten-year real returns (in green). The conclusion is straightforward: when valuations are low, future returns tend to be above average; when valuations are high, forward returns tend to be much more muted.
Right now, the U.S. market sits at a CAPE ratio of around 40. It’s nearly double the long-term average of roughly 20, and the second most expensive in history.
historically, when valuations have climbed to this level, the following decade hasn’t been kind to investors. Not once has a country that ended a year with a CAPE above 40 produced positive real returns over the next ten years. That’s not a personal opinion but what the data shows.
To get a sense of what current valuations might mean going forward, I ran a linear regression using historical CAPE data and forward ten-year real returns. The relationship is remarkably consistent: as valuations rise, future returns fall. At today’s valuation levels, the regression suggests an expected real return of -2.46% for the next decade. From a historical perspective, the last time we were at the CAPE reading we find ourselves in today, the market went on to lose -2.11% per year for the next ten years.
Valuation isn’t the only red flag flashing. Today, about 40% of the market is concentrated in its 10 largest companies. This is the most concentrated the market has ever been.
Concentration itself isn’t a bearish sign. What really matters is how concentration changes going forward. Rising concentration tends to coincide with strong market performance as leading firms continue to gain share and deliver growth. On the other hand, when concentration starts to fall, this means your largest players are underperfoming the rest of your portfolio, and that’s when returns have historically suffered. If the biggest names continue to pull away from the pack, the market could remain strong for a while. But if that leadership falters, history suggests the unwind can be painful.
A few highlights from one of the best articles I’ve read this year discussing the private equity/credit bubble:
The golden age of Private Equity – at least from the standpoint of investor returns (FUM and thus fees to sponsors were significantly lower) – was during 1980-2000, and at a slight stretch, to around the time of the Great Financial Crisis in 2008. During this era, PE delivered legitimately good returns – in some cases outstandingly so. What enabled it was that it was still a niche industry where there was a limited amount of capital chasing deals, while the backdrop was conductive.
In contrast to the 1980-2000s, private equity funds from the 2010s began paying a premium to public market valuations for (typically) small, subscale and illiquid businesses. The problem was that the same thing that always happens when too much money floods into an area happened – bidding competition heated up, target prices rose, and the opportunity that previously existed rapidly disappeared (though the vehicles’ high fee structures of course remained firmly intact). Not surprisingly, since the 2010s, and perhaps as far back as 2006, outcomes have dramatically changed, and PE has delivered generally disappointing returns and underperformed listed equities, and the magnitude of that underperformance has significantly worsened since 2022.
Warren Buffett has scrutinized PEs return calculations and found them to be “well, they’re not calculated in a manner that I would regard as honest.” All kinds of tricks can be and are used to inflate apparent relative returns. PE will often lock up commitments from investors years in advance, and only “call” the funds much later after a deal is done. The IRR calculations only include the period during which the funds are working, but investors need to keep cash in reserve as it can be called at any time, meaningfully diluting effective returns to investors.
The much bigger elephant in the room – the PE industry is currently “marking to model” and is sitting on a vast number of assets it is unable to sell – even in a bull market – because the marks are unrealistic. This will be meaningfully inflating claimed trailing returns, which remain mostly unrealized.
If you look at who private equity companies hire, it is typically ex investment bankers. These guys are deal makers and spreadsheet jockeys, not operational people, and there is no reason to believe they have any unique insights on the intricacies of running small, niche businesses, where specialized skills and decades of domain experience generally count for a lot more than general smarts.
Not to mention that as the industry has mushroomed in size, the average quality of the average hire has meaningfully degraded. Investment bankers also generally lack investment acumen. They are deal makers – a different skill set entirely.
Going even a step further – it’s probable that private equity ownership not only fails to deliver operational improvements, but very likely on net makes the operational performance of companies worse, particularly in the long term. The most obvious means by which this occurs is by saddling investees with significant levels of debt, as well as implementing wholesale asset stripping (such selling and leasing back real estate) and cutting operational costs and capital expenditures to the bone. They frequently don’t just cut the fat, but the muscle as well.
If you are apt to under invest and run the business for maximum cash extraction in the near term, jacking up prices, lowering service quality, squeezing employees, alienating customers and opening the door to competitor inroads – it may improve near term cash generation, but it often comes at the cost of long-term value degradation.
PE has now taken over a large portion of Las Vegas, for instance, and visitors routinely complain of high prices, poor customer service, and the removal of perks such as free drinks that previously endeared visitors to the strip. Visitation has been waning, and people complain Vegas has lost its charm, and has become overpriced and soulless, a victim of “corporate greed.”
This is far from the only example. Employees and customers of PE backed hospitals and dental practices often complain of declining service standards, high prices, and a significant increase in unnecessary treatments unethically prescribed to boost near term utilization/billing.
The fair value of the combined $5 trillion of assets held in the US Private Equity/Credit industry is probably worth only about 60% of that in reality – a $2 trillion hole. When that hole is exposed, it will change economic behavior, and likely to a noticeable degree.
(1) The number of 55+ yard field goals has increased by 3x since just 2022:
(2) Between longer field goals and the dynamic kickoff, the field has basically been shortened by 10-15 yards.
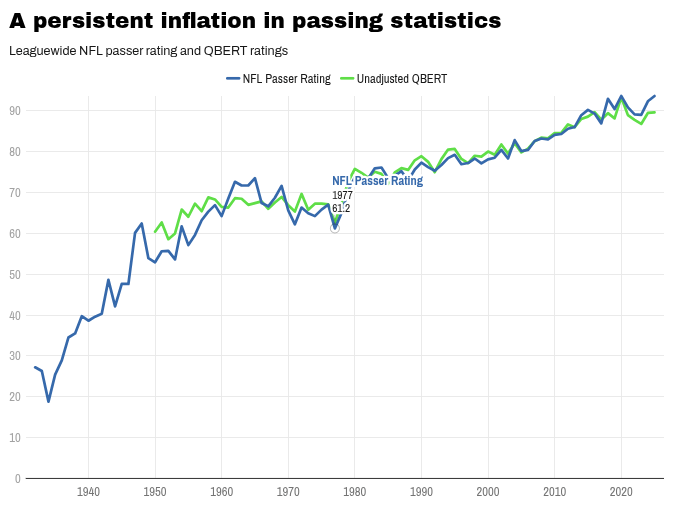
(3) Quarterback passer ratings are tied for their highest-ever at 93.6:
(4) For the first time in NFL history, quarterbacks as a collective are gaining enough rushing yards to outweigh the yards they lose from sacks:
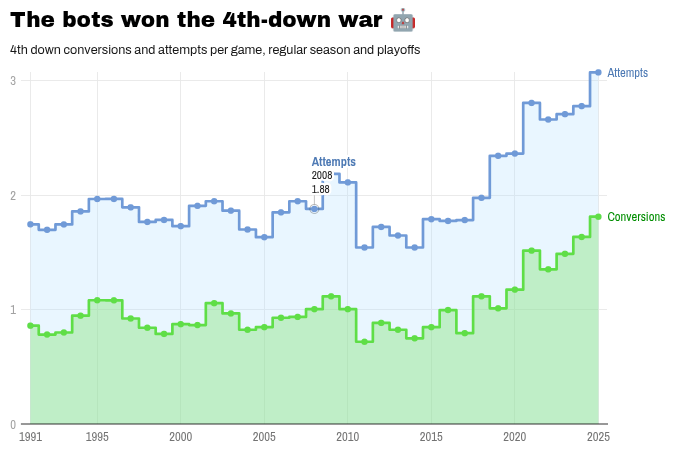
(5) Analytics have teams successfully attempting and completing fourth down conversions:
(6) Rushing plays on 4th-and-short are being attempted (and succeeding) at extremely high rates. The tush push effect:
_______________________
If you’ve ever received a spammy text falsely alerting you to an unpaid toll or failed delivery, it might have come from a so-called Phishing-as-a-Service network that Google is now trying to take down. In just 20 days, Google alleges, Lighthouse was used to spin up 200,000 fraudulent websites to attract over a million potential victims. It estimates that somewhere between 12.7 million and 115 million credit cards in the US were compromised by the scam.
Hyperscalers (Microsoft, Amazon, Google, Oracle, IBM) believe they might build God within the next few years. That’s one of the main reasons they’re spending billions on AI, soon trillions. They think it will take us just a handful of years to get to AGI—Artificial General Intelligence, the moment when an AI can do nearly all virtual human tasks better than nearly any human.
They think it’s a straight shot from there to super-intelligence—an AI that is so much more intelligent than humans that we can’t even fathom how it thinks. A God. The arguments to claim we’re about to make gods are:
AI expertise is growing inexorably. Threshold after threshold, discipline after discipline, it masters it, and then beats humans at it.
We’re now tackling the PhD level.
In the current trajectory, we should reach AI Researcher levels soon.
Once we do, we can automate AI research and turbo-boost it.
If we do that, super-intelligence should be around the corner.
Imagine you are a new college grad from a middle-class family. If you are lucky, you have no education debt, but many do. If you are lucky, you land a 100k+ job, but many don’t. Even if you are lucky, you still look up at astronomical asset prices (houses) and try to work out how you can maybe afford one in 20 years, with the understanding that they will only continue to go up in the meantime.
You are surrounded by online examples of success (usually fake or survivorship bias). Your attention span has been fried by TikTok and YouTube shorts. You simply don’t have the patience or discipline for the slow path.
So instead, you start taking outsized risks with your monthly paychecks – crypto, options, meme stocks, meme coins, sports betting. Your rationale is that this current amount could never buy a house, but if you win it might. And if you lose, you simply have to wait a week or two before you can reload and try again. This is “hyper-gambling.”
The obvious downside of taking repeated high-risk investments is that most will fail in this lottery strategy, and if you find yourself at the end of the tunnel with no diamonds to show for it, you will be even farther behind.
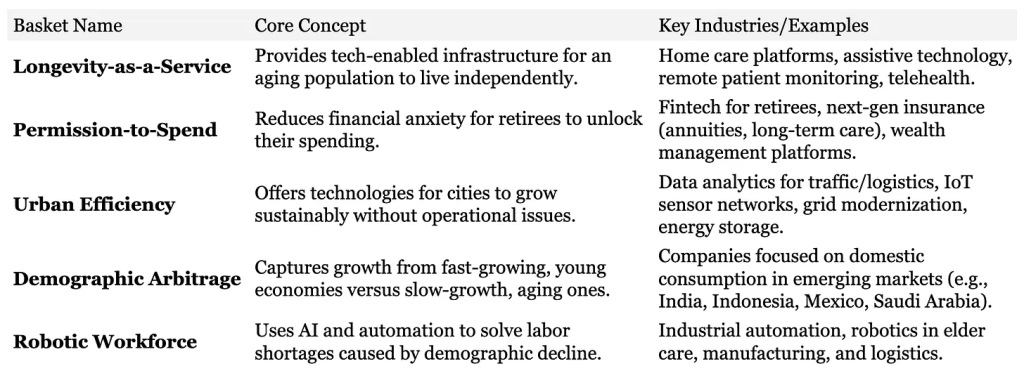
Between 2015 and 2050, the proportion of the global population over 60 is set to nearly double, climbing from 12% to 22%. The most extreme changes though, are happening at the upper end of the age spectrum. The number of individuals aged 80 or older is projected to triple between 2020 and 2050, reaching 426 million. This is exponential acceleration, and two-thirds of the world’s elderly will live in developing nations, up from just over half today.
Running parallel to the aging of the globe is a second, equally powerful human migration: the mass movement into cities. Today, 58% of the world’s 8 billion people live in urban areas. By 2050 this figure is projected to climb to 70%. Nearly 90% of this 2.5 billion-person increase in cities will occur in Asia and Africa. India, China, and Nigeria. are projected to account for over a third of all new urban dwellers globally.
President Clinton noted in his January 2000 State of the Union speech:
“We begin the new century with over 20 million new jobs; the fastest economic growth in more than 30 years; the lowest unemployment rates in 30 years; the lowest poverty rates in 20 years; the lowest African-American and Hispanic unemployment rates on record; the first back-to-back surpluses in 42 years; and next month, America will achieve the longest period of economic growth in our entire history.”
That wasn’t an exaggeration. But it marked the beginning of the worst decade for the U.S. stock market in modern times.
In January 2010, President Obama noted in his State of the Union speech:
“One in 10 Americans still cannot find work. Many businesses have shuttered. Home values have declined. Small towns and rural communities have been hit especially hard. And for those who’d already known poverty, life has become that much harder.”
That wasn’t an exaggeration. But it marked the beginning of one of the best 15 years (and counting) for the U.S. stock market in history.
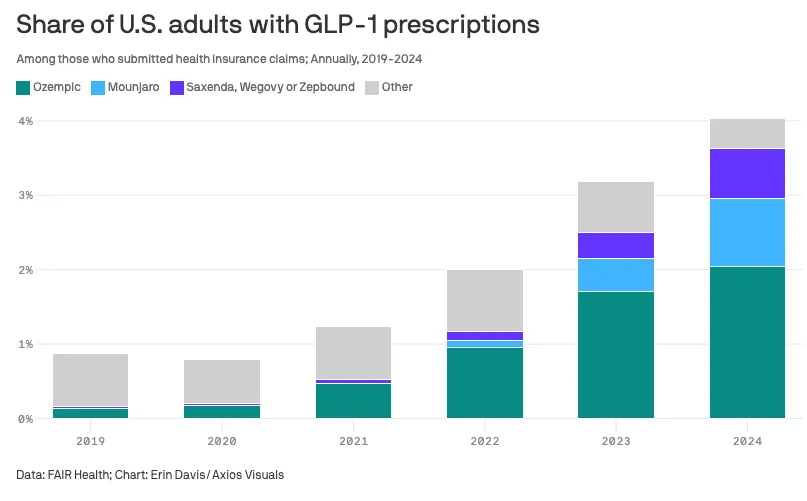
In the last two decades, the share of American adults who say they exercise or play sports on any given day has increased by about 20 percent.
The share of Americans who say they don’t regularly work out or play sports, which SFIA calls the “inactivity rate,” has fallen by more than one-fifth since 2019.
Rich and young Americans exercise the most. Poor and older Americans work out the least. Among adults, income predicts activity better than age.
The increase in exercise minutes is significantly led by young people and women over 65, who increased their weekly workouts by about twice as much as men over 65.
No fitness activity saw a larger increase in participation between 2019 and 2024 than Pilates. Yoga and barre were close behind among the fastest-growing activities. Meanwhile, group cycling, cardio kickboxing, boot camps, and cross-training workouts like CrossFit got walloped by the pandemic, and they haven’t bounced back. In general, Americans seem to have traded sweaty group classes for gentler core work.
After persevering through a valley of tears since 2010, value investors are finally beginning to reap a fruitful harvest in developed international markets. Over the past five years, the value premium has returned to positive territory in international markets as value stocks have returned to outpacing growth stocks. Since July 2020, value has outperformed growth by 11.6% annualized in developed international markets:
Mastroianni: It seems like the takeaway from this research that has been done over the past 10 years or so is that people are way too negative about their own social abilities and the things that are likely to happen when they talk, especially to someone new. So, for instance, they underestimate how pleasant it’s going to be to talk to someone new. But even afterward, when we ask them, hey, how much did you like that person? They say oh, I like them a lot. And when we ask, how much did they like you? Oh, less than that. I ran one study with some friends of mine where we had people talking groups of three and we’re like, okay, how much did you like them? People would say 5 or 6 out of 7. And how much did they like you? People would say 4 or 5 out of 7. On average, people thought they were the least liked person in the conversation, which obviously can’t be true for each person.
Thompson: We are, on the one hand, the social animal. Yet we delude ourselves about the degree to which we’re a fun hang. We’re the social species and we’re the socially anxious species as well.
Mastroianni: Yeah, well, we’re the ones who care about it the most. And so we have the most to lose. And so we worry about it the most in part in the hopes that maybe it makes us better at doing it. The way I think about it is in our evolutionary history, we lived in groups. But how often did we meet someone who we literally had no connection to before? I can’t imagine it was all that often. But today it can happen literally every day. You get on the bus and it’s full of people that aren’t related to you. You don’t know them. They don’t know you. That’s a really weird thing to do.
____________________________________
Morgan Stanley surveyed all stocks trading on U.S. exchanges over a 40-year period, between 1985 and 2024. They found the median stock experienced a decline of 85% at one point or another. Worse yet, more than half of these stocks never fully recouped their losses. The median stock recovered to just 90% of its prior high-water mark. Among those stocks that were able to reclaim their prior highs, it was a long process—about five years, on average.
Those numbers only apply to the median stock, but suppose you had above-average stock-picking skills. How would things have turned out? If you had the foresight to pick the 20 best performing stocks over that 40-year period, at some point they still would have delivered an average agonizing draw-down of 72%.
It’s hard to remember, but Apple dropped 83% at one point. Nike once lost 66%. Even Nvidia, which was the best performing stock over the past 20 years through 2024, lost more than 90% at one point. And most notably, Amazon was once down 95% from its prior high.
Over the long term, share prices tend to move in tandem with corporate profits. When a company’s earnings increase, often its share price does too. The problem is that prices are only sometimes rational. Very often, stock prices disconnect from corporate earnings, and the gap can be significant.
This was first proven empirically Daniel Kahneman and Amos Tversky. In 1974, they published a paper that found investors exhibit an “availability heuristic.” That is, they tend to rely on the information that is most available. That’s a problem because the information that happens to be most available isn’t necessarily the information that’s the most accurate or even relevant. Often, the information that happens to come to mind is the information that’s most vivid. In other words, extreme information or news becomes most memorable, and thus drives decision-making.
___________________________
ChatGPT users may want to think twice before turning to their AI app for therapy or other kinds of emotional support. Sam Altman, OpenAI’s CEO:
“People talk about the most personal sh** in their lives to ChatGPT. People use it — young people, especially, use it — as a therapist, a life coach; having these relationship problems and [asking] ‘what should I do?’ And right now, if you talk to a therapist or a lawyer or a doctor about those problems, there’s legal privilege for it. There’s doctor-patient confidentiality, there’s legal confidentiality, whatever. And we haven’t figured that out yet for when you talk to ChatGPT. This could create a privacy concern for users in the case of a lawsuit, because OpenAI would be legally required to produce those conversations today.“
The 1990s were a turning point for country’s mainstream acceptance, driven by two mutually reinforcing phenomena:
Improved Telecommunication Infrastructure: The Telecommunications Act of 1996 enabled American media companies to consolidate regional stations into national networks, facilitating country radio play outside of rural strongholds. Simultaneously, enhanced geographic radio coverage brought consistent access to under-served rural listeners. Together, these infrastructure improvements fostered a virtuous cycle: greater airplay propelled more country songs onto the charts, which in turn drove even more airplay.
Country Crossover Successes: Country crossovers like Garth Brooks, Shania Twain, and Tim McGraw blended conventional genre staples with accessible pop and rock influences, broadening the format’s appeal beyond its traditional fanbase.
______________________________________
Something unusual—and incredibly fast—is happening with teenagers running the 100-meter around the world. From Japan to the U.K., young speedsters are posting eye-popping times in track’s most prestigious event. What’s driving these turbocharged athletes who aren’t old enough to vote?
Peter Bernstein liked to say that investors have memory banks: the market returns collectively earned by people of similar age. Experience shapes expectations. The problem is that your memory bank can deceive you in dangerous ways. Your experience of the past is a reasonable guide to the future only if the future turns out to resemble the portion of the past that you’ve lived through. And it often doesn’t. It’s worth looking at a few investing beliefs that your memory bank might hold—and asking whether they’re still valid.
_______________________________
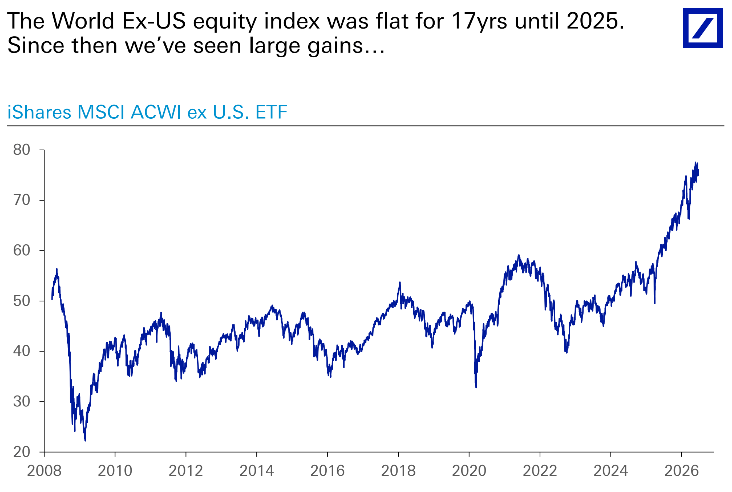
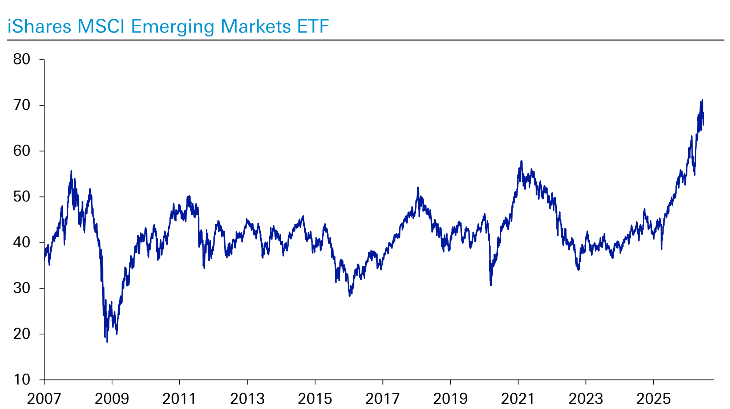
How much longer will emerging markets be undervalued and hated?
________________________________
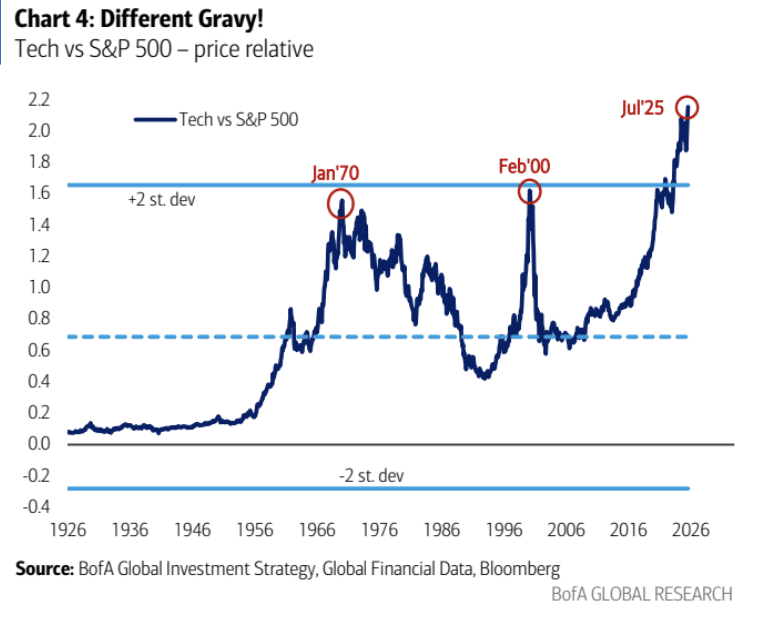
Nasdaq Price to Earnings valuations are at the very high end of their historical range. That means they are extremely expensive.
While countries like the United States and India are extremely expensive relative to the rest of the world, the global stock market as a whole has seen its P/E ratio rise dramatically from the early 2010s.
_______________________________
Looking at Enterprise Value (EV) divided by sales, we’re not above the 2000 and 2021 bubble peak for global stocks:
“When (Charlie Munger and I) were born the odds were over 30-to-1 against being born in the United States. Just winning that portion of the lottery, enormous plus. We wouldn’t be worth a damn in Afghanistan. We won it partially in the era in which we were born by being born male. We won it in another way by being wired in a certain way, which we had nothing to do with, that happens to enable us to be good at valuing businesses. And you know, is that the greatest talent in the world? No. It just happens to be something that pays off like crazy in this system.”
If you had invested from 1960 to 1980 and beaten the market (the S&P 500) by 5% each year, you would have made less money than if you had invested from 1980-2000 and under-performed the market by 5% every year. When you start investing can be more important than anything else.
_______________________________________
For years, 529 accounts were synonymous with college savings plans. But recent updates have given the accounts a makeover. They’ve become education savings accounts, not just college savings accounts. The latest change allows the accounts to be used to help pay for a broader range of post-high school credentials, like certification in specialties like auto mechanics or food safety,and related expenses.
Population ageing and decline is one of the most powerful forces in the world, shaping everything from economics to politics and the environment. It it implies the goal is the same today as it was in the past: finding ways to encourage couples to have more children. A closer look at the data suggests a whole new challenge.
Take the US as an example. Between 1960 and 1980, the average number of children born to a woman halved from almost four to two, even as the share of women in married couples edged only modestly lower. There were still plenty of couples in happy, stable relationships. They were just electing to have smaller families.
When you ask people, “What builds wealth?” you get a wide variety of answers. Some will tell you it’s mindset. Some will say work ethic. Some will say it’s spending. And a host of other explanations. If you could have just one piece of information on somebody to predict their future wealth, what would it be? Would you ask for their IQ? Whether they went to college? How about their parents’ education level?
The answer is the most obvious and straightforward: For someone of working age, their income is the best leading indicator of wealth. What leads to higher income? Hard work, connections, and luck are important, but high earners tend to follow one of four distinct paths. These paths won’t guarantee success, but they are where high incomes tend to cluster:
Sales and Persuasion
Technical/Analytical Skills
Advanced Degrees/Credentials
Entrepreneurship and Business Building
______________________________
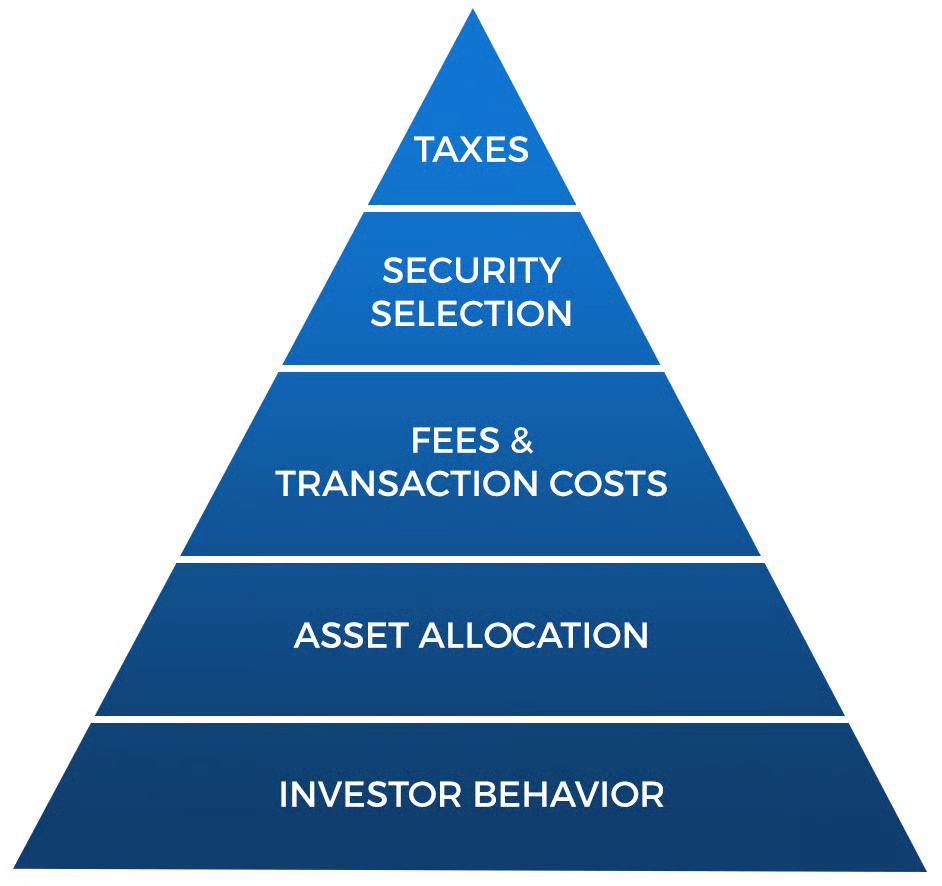
Some investing skills have to be mastered before any other skills matter at all. There is a hierarchy of needs.
At the foundation of this hierarchy are the boring but essential behaviors: living below your means, having an emergency fund, staying invested during downturns, and picking a reasonable asset allocation. These things aren’t exciting. They won’t get you likes. But they will carry you through decades of compounding.
Higher up the hierarchy are things like choosing the right stocks or funds and minimizing fees. These are useful, but only after the foundation is strong. Otherwise, you’re just rearranging furniture in a house with shaky walls.